

Disclaimer: By reading this article, you acknowledge and agree to the terms and conditions
Introduction
AI this, Nvidia that, it’s getting pretty tiring, isn’t it? Almost like Tariffs back in April 2025 or Iranian Twitter Posts in March 2026, every tidbit of AI related news is met by market participants with a groan and a Tylenol. By Friday at 4:00 PM, you’re just glad you get 50 hours of peace and quiet before Trillion dollar tech giants act like crypto coins again (equities open at 6 PM these days - thank you IBKR for deciding 24/5 trading is what everyone really wanted).
If you’re getting sick of it, and invest Internationally, perhaps this post is for you.
A major source of diversification and performance in my Portfolio has been International small caps - cash gushing businesses at extremely low multiples with a proven track record of growth, management alignment, and crucially, sizeable shareholder return programs. The nice thing about these holdings is they tend to have a mind of their own: they’re boring businesses entirely unaffiliated with AI, and are minimally correlated to broader indices.
To give background on a few of my favorites: Georgia Capital has a large position in Georgia’s largest bank (Lion Finance Group) and a portfolio of Pharmacies, Insurers, and Hospitals, Ambea is the largest operator of Mental Healthcare Homes in Sweden, Halyk Savings Bank is a Kazakh Financial Giant with a huge dividend, SE Holdings and Incubations (9478) runs a Japanese publishing business with a huge cash balance and investment Portfolio, ABC Arbitrage runs two statistical arbitrage hedge funds (both of which are up 30% YTD), and Kaspi manages a Kazakh superapp encompassing grocery delivery, e-commerce, fintech, travel, and even government services (imagine applying for a Driver’s License via Uber).
I don’t mention these businesses to try to intentionally be “niche” - I’m simply trying to point out that what they focus on is unrelated to AI or noticeable factors. Whether Nvidia loses ground to AMD or Google, or interest rates tick up another 25 bps in December, it doesn’t have much of an impact, and that’s what I like about them.
These days factor whipsaw is immense: banks, insurers, and even staples like Clorox and Campbell’s Soup roar every time Nvidia or the neoclouds get taken behind the barn, and vice versa. The swings are nauseating. Are Clorox or Walmart justifiably worth 25% more because Jensen had an affair? In my opinion, probably not, but as long as traders who are long AI and short everything else keep degrossing, the craziness can continue.
The allure of these International value setups, on the other hand, is that they are distanced enough to avoid the daily factor cage fight - chances are you’ve never heard of these names before, and neither has the market. The beauty of this is that rather than have your account’s value tied to whether the WSJ writes another Nvidia hit piece, you can take stances on single names that pay off as long as the businesses keep making progress. It’s stock picking in its truest form.
These International Value setups are all on track for record profitability and cash returns this year. Georgia Capital, SE Holdings, and Ambea have repurchased 5-15% of their float in the first 9 months of 2026, and ABC Arbitrage, Kaspi, and Halyk are paying dividends of 7.5%, 10.5%, and 14.6%, respectively. The market is increasingly appreciative of their solid financial performance and shareholder friendly capital allocation, and all 6 have generated outsized returns while side stepping gut wrenching volatility (ABCA is a new position from September).
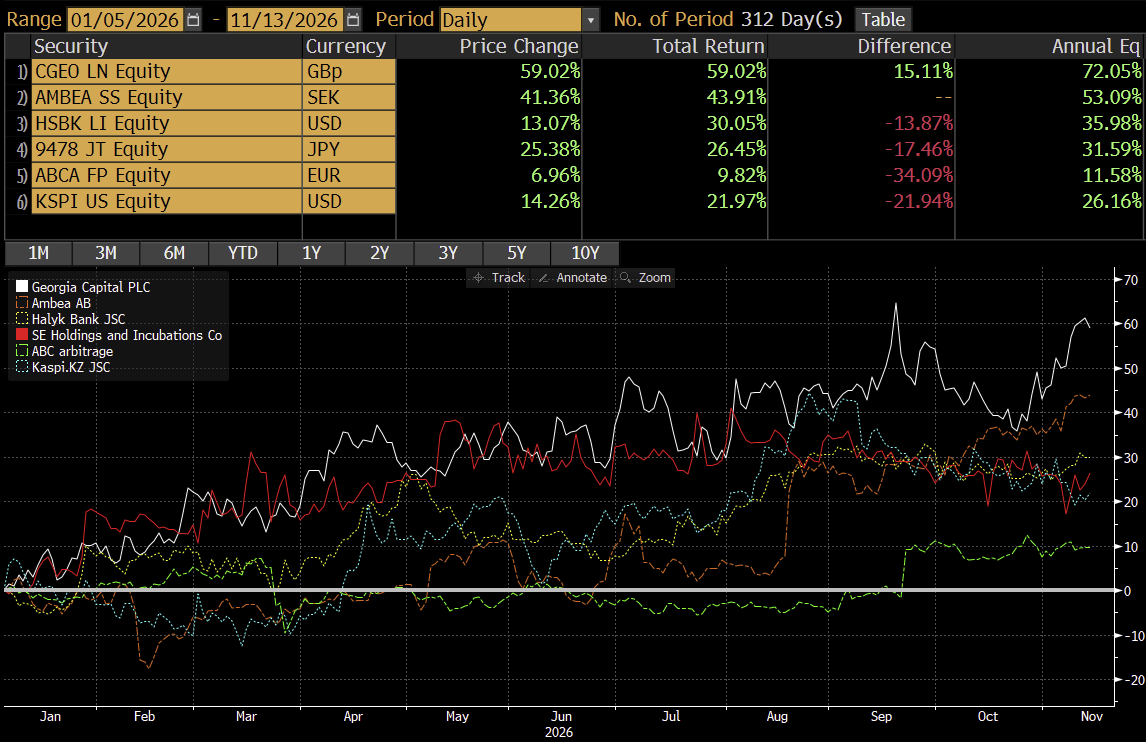
I’m always looking to add names that follow the framework of Consistent Earnings, Management Alignment, and Shareholder Friendly Capital Allocation to diversify my Portfolio, but these days it’s hard to find names that fully fit the criteria. One of the countries I’ve been scouring for these setups is, surprisingly, Korea.
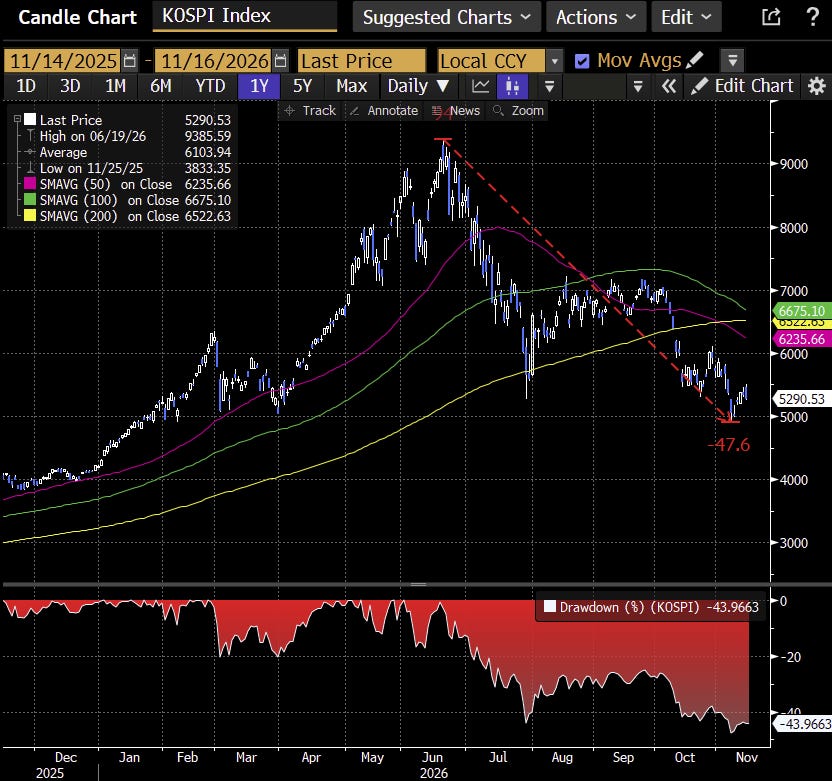
Since the June peak the Kospi is down 43%, and many value setups entirely unaffiliated with AI are getting tossed out with the bath water. What’s interesting about Korea is that there’s unprecedented visibility into capital allocation. Many Korean equities publish a “Value Up” program where they commit to P/B, ROE, and payout ratio targets, and more importantly, publish buyback orders in advance of executing them on a daily basis.
For value investing, this takes a lot of the guesswork out of determining shareholder friendly capital allocation. Unlike many US value traps where management teams bemoan their stock is undervalued only to sheepishly report 3 months later they didn’t repurchase a single share (looking at you, mREITS and BDCs), in Korea you can immediately spot who is following through on their Value Up Plan.
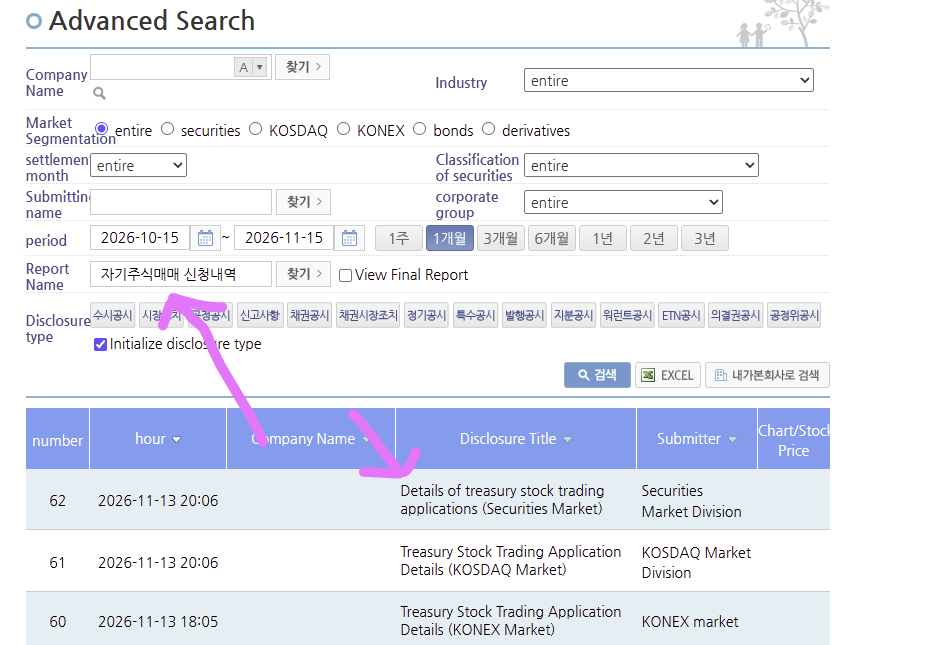
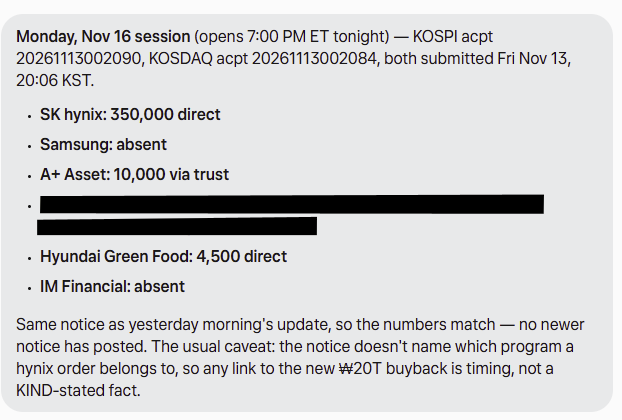
You can query the buyback reports by hand via KRX Kind Filings and typing 자기주식매매 신청내역 in Report Name to access a daily list of share repurchase orders, or you can simply give Meta’s Muse a list of your holdings and ask it to do the work for you! KRX Kind blocks Claude and OpenAI, but Muse’s browser use tool is able to bypass the block, and I’ve given it a list of my Korean holdings and tasked it with sending a daily report on who is repurchasing shares - it works great.
In this piece, I want to get back into deep value investing, and provide earnings updates on three existing Korea value positions that I believe offer a compelling risk-to-reward, as well as a brand new Korea position with 35% of the market cap in cash, significant insider alignment, inflecting growth potential, and crucially, improving capital allocation.
1. Hyundai Green Food (453340 KS Equity)
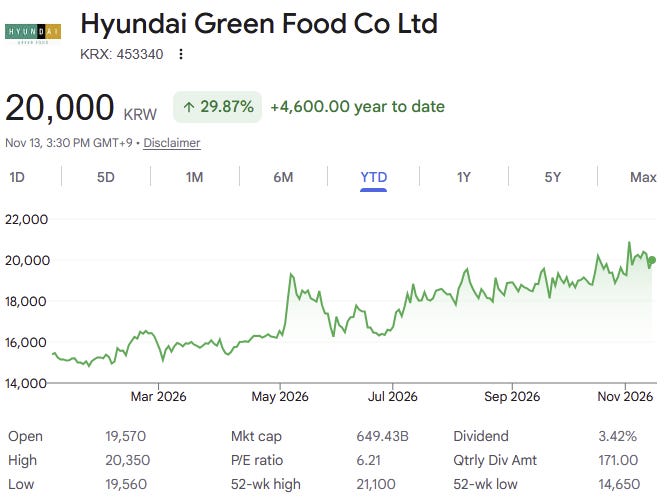
Hyundai Green Food is my favorite Korean Value setup. The company has set several all-time highs since the May write-up as good news continues to roll in.
For those of you who are new to the company, Hyundai Green Food is an extremely simple business: they operate hundreds of corporate cafeterias, supply meals and ingredients to Hospitals and the Korean Military, sell packaged and hot meals throughout Hyundai Department Stores (an affiliate), and exclusively operate a growing Portfolio of Eataly and Texas Roadhouse franchises throughout Korea. On a side note, Texas Roadhouse is a fantastic restaurant.
It’s not the most exciting business, but what I like about Hyundai Green Food is its sustainability. These days, everyone is questioning the sustainability of the Memory trade, the storage trade, even Nvidia itself. There’s a huge amount of uncertainty. Should Nvidia trade at 10x earnings, 8x earnings, will 2028 EPS be $20 or $8? There’s a wide variety of outcomes, which is why the trade feels so toxic.
For Hyundai Green Food, we don’t have this issue. Rain or shine, people need to eat. Hospitals need to serve patients, hungry soldiers need decent meals, and Hyundai’s Department Stores (Hyundai G.F. Holdings 005440 - extremely similar name), are likely to continue their working relationship with Hyundai Green Food given they also own 30% of the company.
Given Hyundai Green Food’s accelerating growth and track record of stable earnings, it feels like the type of name you wouldn’t be surprised to see trading at 10x, 15x, even 20x earnings given American peer Aramark Holdings trades at 23x forward earnings. In contrast Hyundai Green Food trades at just 6.3x trailing earnings, and 6.1x my 2027 forecast of 3,300 Won a share.
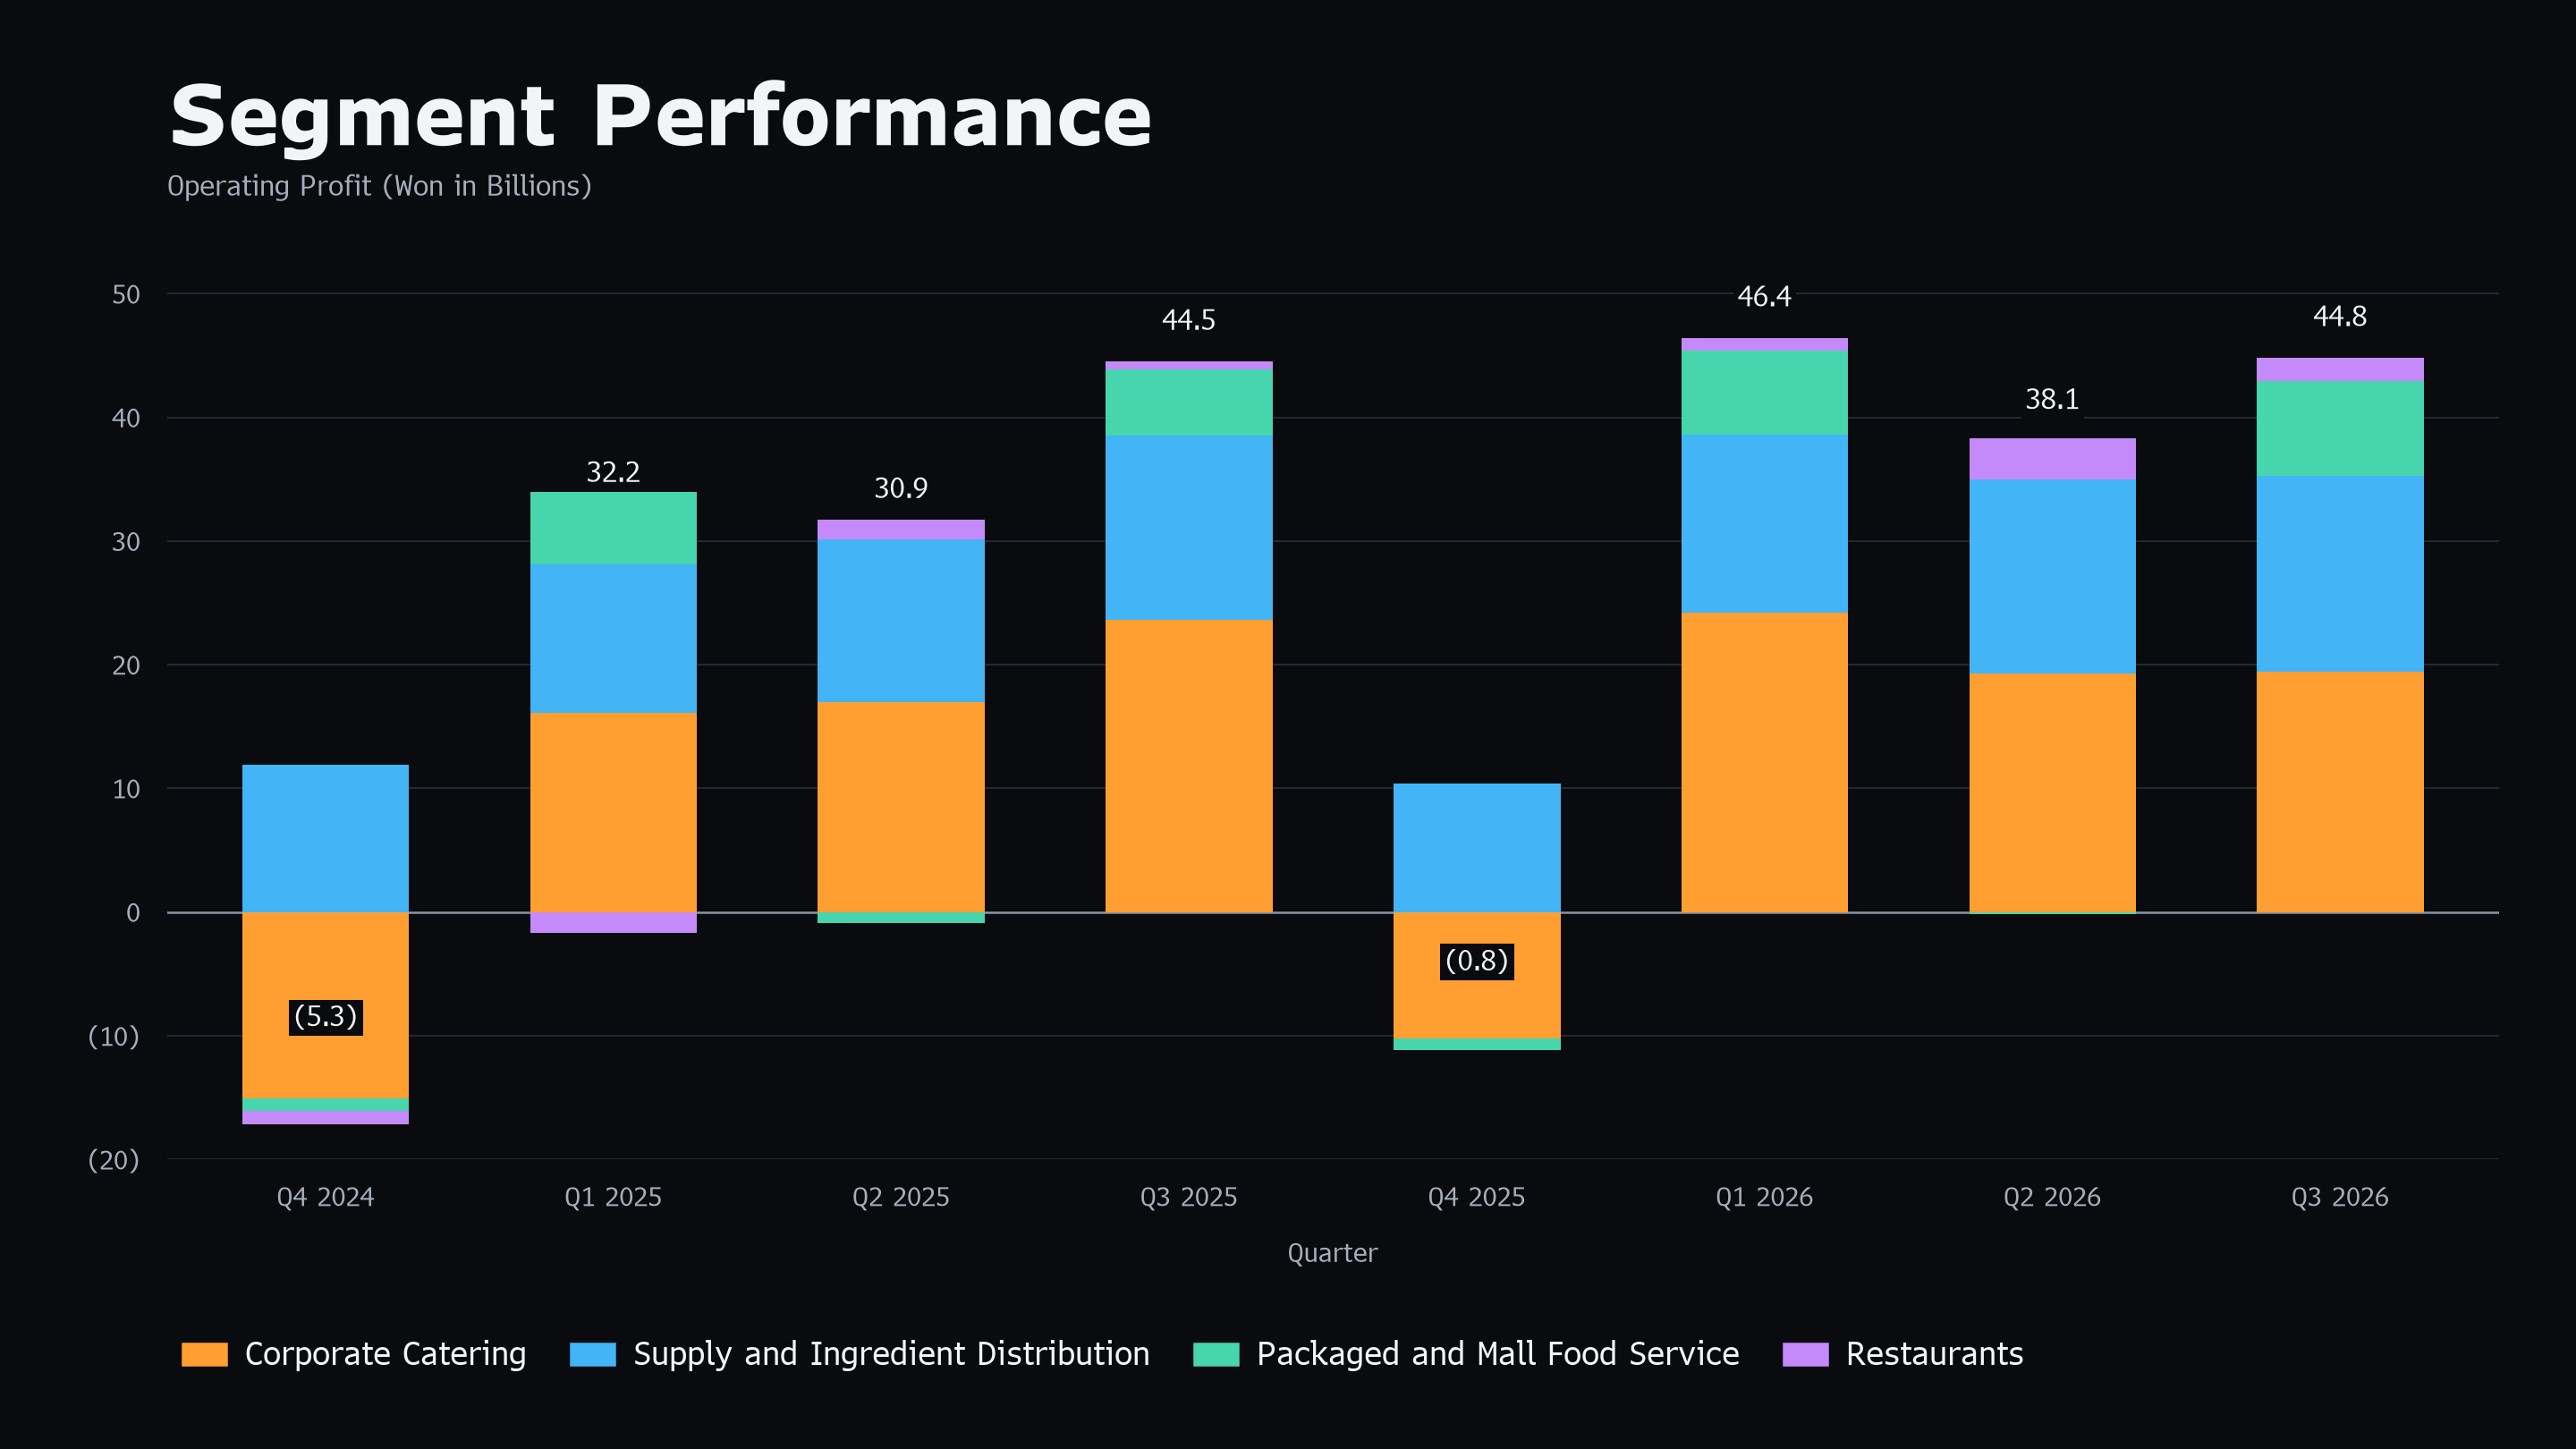
Profitability continues to improve across all of Hyundai Green Food’s segments despite corporate strikes impacting the Corporate Catering segment. Q3 EPS came in at a record 1,080 Won, 9M 2026 revenue and EPS jumped 7.4% and 20% respectively from the comparable period in 2025, and the Restaurant segment is accelerating as additional Texas Roadhouses are opened.
What really piques my interest in the company, however, is its clean balance sheet and shareholder friendly capital allocation. Unlike cheaper peers like CJ Freshway who have significant debt, Hyundai Green Food is capex-light and debt-free, with a net cash position of around 6,000 Won per share.
This makes it easy for the company to continue rewarding loyal shareholders. Hyundai Green Food increased the 2026 dividend by 6% to a record 684 Won (representing a 3.4% yield), and continually repurchases 80,000 - 90,000 shares a month, providing steady upwards pressure on the price and mopping up 10-15% of the average daily volume. Hyundai Green Food is also heavily incentivized to continue returning cash, given its affiliate Hyundai GF Holdings is also increasing its dividend and looking to return more cash to shareholders
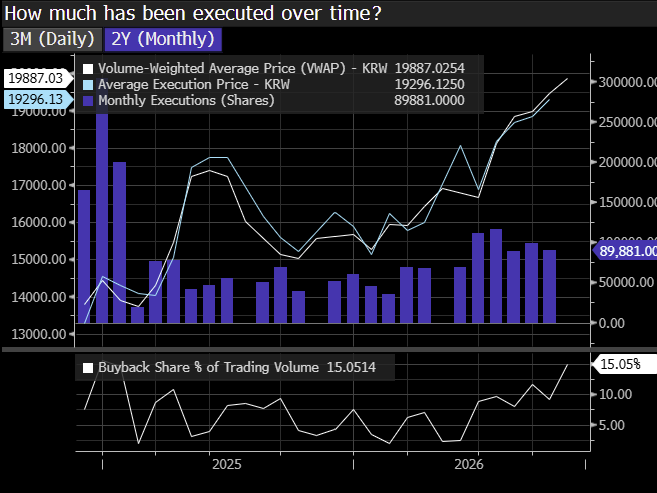
With the stock trading at a discount to its own Tangible Book Value of 20,400 Won per share, it makes sense for the company to continue aggressively repurchasing shares, especially when they have nothing else to do with the sizeable cash pile.
I love these types of setups: Hyundai Green Food is an under-the-radar name with a clean balance sheet, attractive P/E, astute management, growth prospects, and most importantly, is actively returning capital to the shareholders. These types of setups are off-limits to larger Institutional investors who likely have an average daily volume or liquidity mandate, but readily accessible to individual investors, and I think by taking a position in value setups at attractive multiples where you know the company is sitting in the orderbook on a daily basis to repurchase shares, you can tilt the odds in your favor.
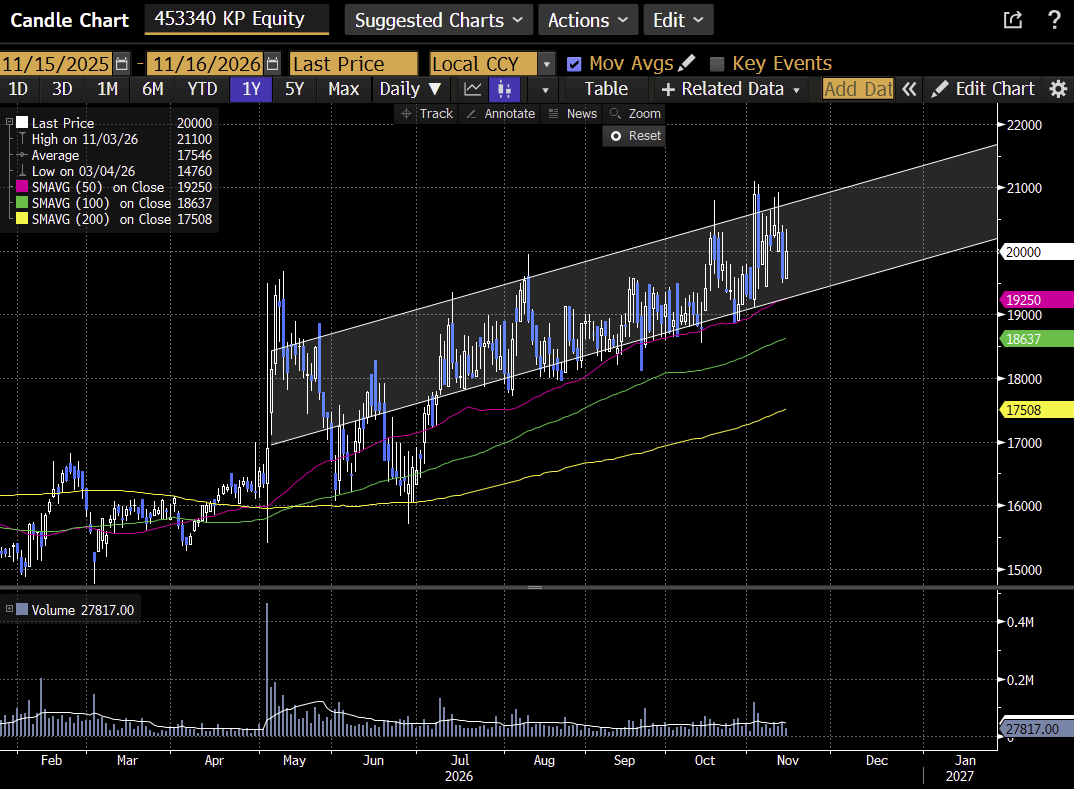
I have been steadily adding to my position in the 19,000 to 20,000 range, and am looking for upside to 25,000 Won a share, which would imply 7.5x 2027 earnings and 1.05x 2027 Tangible Book Value, still an extremely reasonable valuation. Hyundai Green Food is now a high conviction trade for me. I don’t expect a huge return, but at the current valuation I’m happy to add some “quiet value” to my Portfolio that is insulated from AI. Conditions seem primed for a slow grind higher: the company authorized an additional 5.25 Billion Won buyback on November 3, at the current pace of 4,500 shares a day the supportive hand of share repurchases will stretch into January.